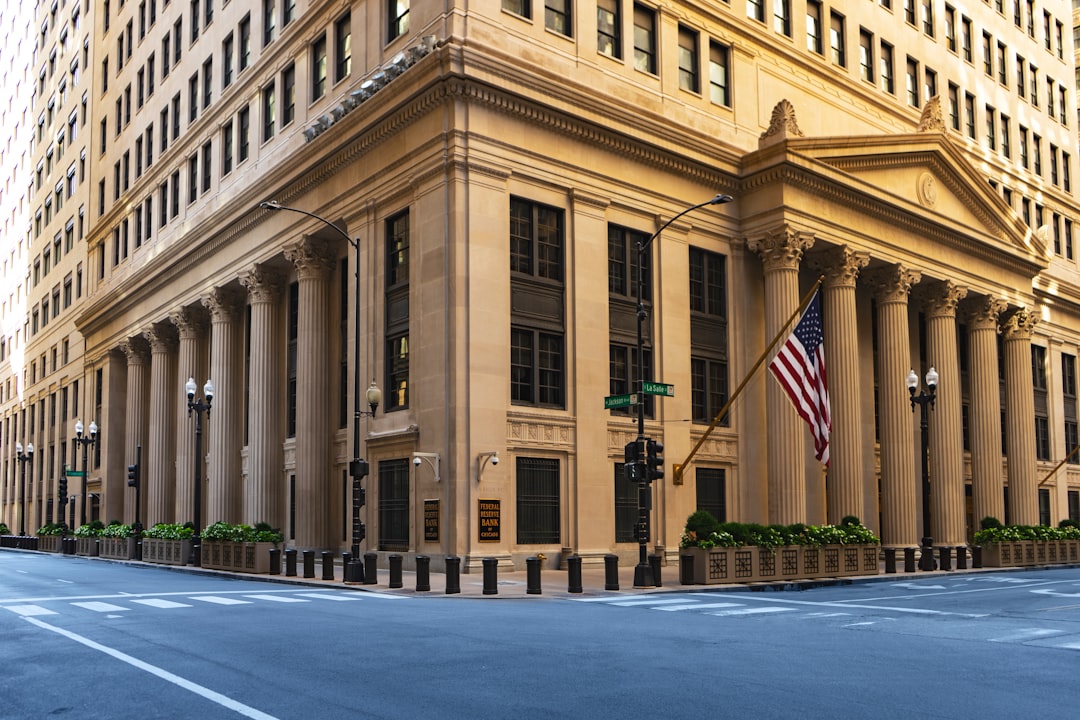
Why Markets Prefer a Hawkish Fed Over Policy Uncertainty: Taking Stock Analysis
The "Taking Stock" column argues that financial markets digest a clearly telegraphed, hawkish Federal Reserve trajectory far better than they tolerate ambiguity around the policy path. The core thesis posits that policy certainty—even when restrictive—allows for efficient risk pricing, while uncertainty paralyzes capital allocation and amplifies volatility across asset classes.

Market Impact & Global Context
Historical precedent supports the column's framework. During the 2022–2023 tightening cycle, the Fed raised rates aggressively yet U.S. equities bottomed in October 2022 once the terminal rate came into focus. Conversely, the 2019 pivot and 2021 "transitory" inflation narrative—periods defined by shifting guidance—triggered violent sector rotations and explained why interest rates are so high through a lens of credibility erosion.
The transmission mechanism operates through three channels. First, forward rate agreements and SOFR futures price efficiently when the dot plot anchors expectations, reducing hedging costs for corporate treasurers. Second, emerging market capital flows stabilize when the Fed's reaction function is predictable; surprise shifts trigger sudden stops and currency crises. Third, bank lending standards tighten procyclically under uncertainty as loan officers demand wider spreads to offset policy model error.
Current dynamics reinforce this reading. The global economy is running out of wiggle room for policy errors, with fiscal dominance concerns in the U.S. and Europe limiting the room for monetary missteps. Meanwhile, Japan raises interest rates to a 31-year high partly because BoJ clarity reduced the risk of a disorderly yen move—a case study in certainty enabling normalization.
"Markets are discounting machines, not forecasting machines. A known 5.5% terminal rate is an input; a terminal rate that could be 4%, 5%, or 6% depending on the next CPI print is a risk factor that forces portfolio de-risking across the board."
— Senior Rates Strategist, Global Macro Desk
Sectoral implications are asymmetric. Rate-sensitive sectors (utilities, REITs, small caps) outperform on certainty because duration risk becomes hedgeable. Growth equities suffer disproportionately under uncertainty as discount rate volatility compounds cash-flow uncertainty. Commodities and inflation-linked bonds gain bid when the Fed's reaction function turns opaque, reflecting embedded inflation risk premium expansion.
Key Takeaways
- Certainty > Level: A transparent, restrictive policy path reduces the equity risk premium more than an opaque, accommodative stance.
- EM Vulnerability: Emerging market sovereign spreads widen 40–60 bps during Fed guidance vacuums, per IMF 2023 spillover studies.
- Bank Credit Channel: Loan officer surveys show lending standards tighten 2–3 quarters earlier when policy uncertainty indices spike.
- Portfolio Construction: Investors should overweight quality factor and short-duration credit when the Fed's dot plot dispersion exceeds 75 bps.
Frequently Asked Questions
Does a hawkish Fed always hurt stock markets?
No. Equities often rally once the terminal rate is priced and the hiking cycle ends, as seen in late 2022. The damage occurs when the path is uncertain, forcing investors to price multiple scenarios simultaneously.
How does Fed uncertainty affect emerging markets differently than developed markets?
Emerging markets face compounding risks: capital flow reversals, currency depreciation, and imported inflation. Developed markets have deeper hedging markets and reserve currencies that absorb shocks more efficiently.