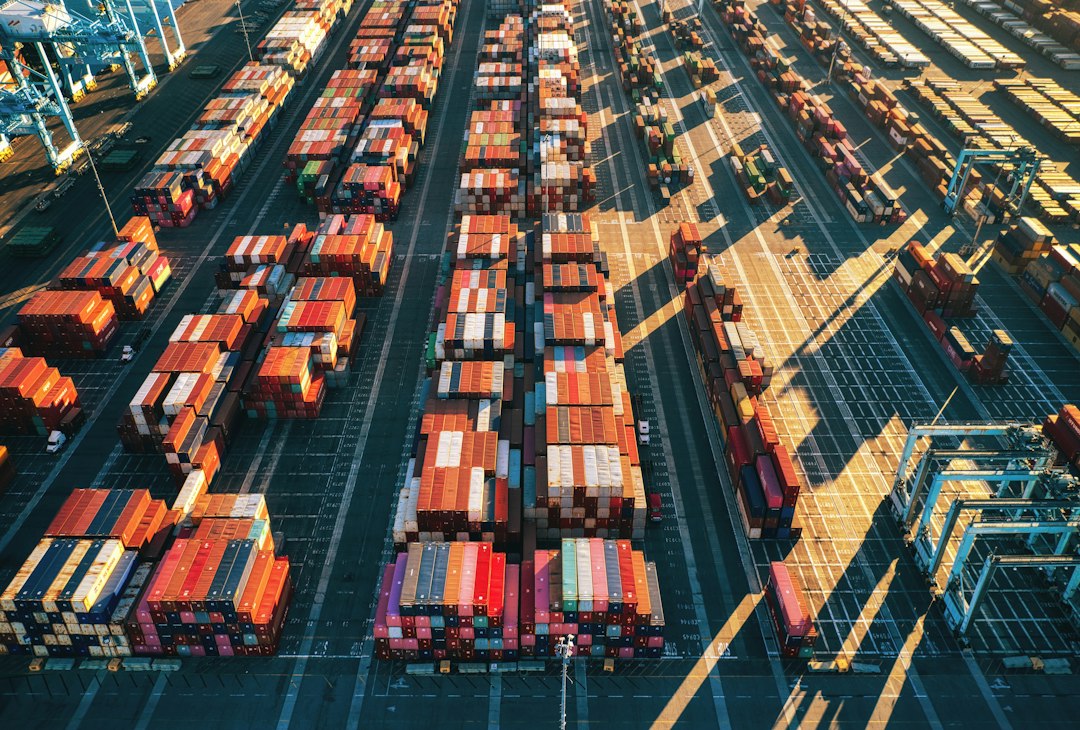
Trump China Industrial Overcapacity Impasse Risks Global Trade War Escalation
The Trump administration confronts a persistent structural challenge: China's massive industrial overcapacity distorts global markets across steel, aluminum, and green technology sectors. This imbalance, inherited from prior administrations, threatens to trigger renewed tariff escalation and supply chain fragmentation according to New York Times reporting.
Market Impact & Global Context
China's excess production capacity exports powerful deflationary impulses through manufactured goods channels, depressing global prices for steel, aluminum, and increasingly for electric vehicles, lithium-ion batteries, and solar photovoltaics. This dynamic undermines domestic producers in the United States and Europe while complicating the Inflation Reduction Act and Green Deal industrial policy objectives. The resulting policy response — typically tariffs and trade remedies — introduces offsetting inflationary pressures on input costs, creating a stagflationary tug-of-war that frustrates Federal Reserve policy calibration.
Historical precedent suggests unilateral tariffs alone fail to absorb structural supply gluts of this magnitude. The 2018 Section 232 measures and the Phase One purchase commitments did not durably reduce Chinese capacity utilization. Current transmission channels now extend beyond traditional metals into strategic technology sectors where overcapacity threatens to derail Western efforts to build resilient, diversified supply chains for critical minerals processing and clean energy manufacturing.
"The core dilemma remains that tariffs alone cannot absorb a structural supply glut of this magnitude," said a senior trade strategist at a major global investment bank. "Without a coordinated OECD framework addressing state-led capacity expansion, capital misallocation risks deepening across the global manufacturing base."
Emerging market economies face asymmetric exposure: commodity exporters benefit from Chinese demand for raw inputs, while manufacturing competitors in Southeast Asia and Latin America confront unfair competition in third markets. Investors should monitor allied coordination efforts — particularly EU anti-subsidy investigations and Japan-Korea alignment — as leading indicators for coordinated trade remedy actions that could reshape sector rotation dynamics across global equities.
Key Takeaways
- China's industrial overcapacity remains a structural, not cyclical, challenge for global trade architecture.
- Tariff escalation risks stagflationary pressures: higher input costs for manufacturers, deflationary goods for consumers.
- Green technology supply chains — specifically EVs, batteries, solar, and critical minerals — face the most acute distortion from subsidized Chinese overproduction.
- Allied coordination on trade remedies (EU, Japan, Korea) serves as the critical leading indicator for coordinated policy response.
Frequently Asked Questions
How does China's industrial overcapacity affect US inflation?
China's excess production exports deflationary pressure via cheap manufactured goods, lowering consumer price inflation for durable goods. However, retaliatory tariffs imposed to counter this surge raise input costs for US producers, creating a stagflationary tug-of-war that complicates Federal Reserve policy calibration.
Which sectors face the highest exposure to Chinese overcapacity in 2026?
The green transition supply chain — specifically electric vehicles, lithium-ion batteries, solar photovoltaics, and critical minerals processing — faces the most acute distortion. Traditional sectors like steel and aluminum remain structurally oversupplied, but policy focus has shifted decisively toward strategic technology sectors where overcapacity threatens domestic industrial policy objectives.