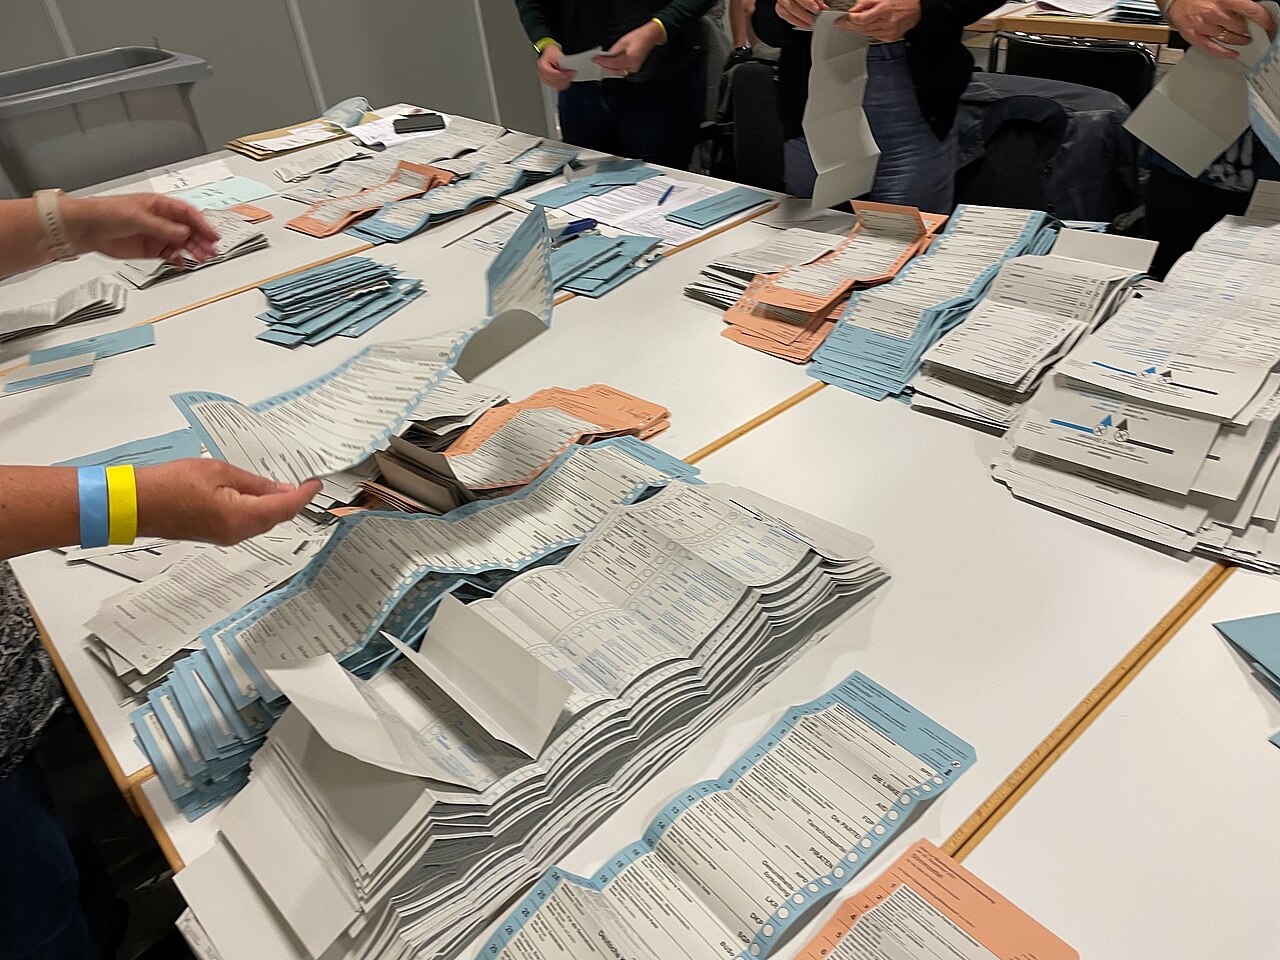
The Left Party secured victory in Berlin while the Alternative for Germany prevailed in Saxony-Anhalt, prompting former CDU chairwoman Annegret Kramp-Karrenbauer to warn that governance by either party would profoundly alter citizens' lives. The dual outcomes underscore fragmenting voter alignment in Europe's largest economy.
Germany's fragmented regional verdicts amplify coalition uncertainty at a time when the traffic-light federal government already navigates fiscal consolidation and industrial competitiveness challenges. Historically, state-level AfD breakthroughs have widened Bund-BTP spreads as investors price policy unpredictability, while Left Party executive participation raises questions regarding expropriation risk and corporate taxation trajectories. The euro's interest-rate differential versus the dollar remains sensitive to Bundesrat composition shifts that could stall or accelerate structural reforms. Portfolio managers are reassessing duration exposure in German sovereigns and recalibrating DAX sector weightings, particularly in energy-intensive industrials and residential real estate where regulatory overhang is most acute.
The market is not pricing a regime change but a widening distribution of policy outcomes; that asymmetry keeps volatility bid across German risk assets.
Credit strategists note that sub-sovereign issuance from Berlin and Magdeburg may face concession demands at upcoming auctions, while the European Central Bank's transmission protection instrument provides a backstop that caps tail-risk premia. Sector rotation toward domestic defensives — utilities, healthcare, and telecoms — has accelerated in early trade, reflecting a flight to regulatory visibility amid coalition arithmetic complexity.
Market Impact & Transmission Channels
Political fragmentation transmits through three primary channels: sovereign risk repricing via Bund asymptote shifts, equity risk premium expansion for domestically exposed mid-caps, and euro cross volatility as coalition timelines extend. The AfD's Saxony-Anhalt win complicates federal-state coordination on energy transition funding, pressuring green bond spreads. Simultaneously, Left Party influence in Berlin's housing portfolio revives rent-cap discourse, depressing Vonovia and Deutsche Wohnen valuations. Foreign portfolio flows into German equities have slowed since the 2021 federal election; these results risk extending the underweight bias.
Key Takeaways for Investors
- Monitor: Bund-BTP spread trajectory and 10-year Bund auction bid-to-cover ratios for signs of sovereign concession pricing.
- Expect: Elevated implied volatility on DAX index options through coalition negotiation windows in both states.
- Assess: Residential REIT balance-sheet sensitivity to potential Berlin rent-regulation tightening under Left Party participation.
- Evaluate: Overweight positioning in German export-oriented large-caps with minimal domestic regulatory exposure as a hedge against coalition gridlock.
Frequently Asked Questions
How do German state elections influence federal policy and financial markets?
State results determine Bundesrat composition, which must approve legislation affecting finance, tax, and energy policy. Strong AfD or Left Party showings constrain federal coalition options and amplify policy uncertainty, prompting risk premium adjustments across German sovereigns, equities, and the euro.
What historical precedent exists for AfD electoral gains impacting Bund yields?
Previous AfD breakthroughs in Thuringia (2019) and Saxony (2019) coincided with 8-12 basis point Bund yield compression relative to swaps as investors sought safety, while peripheral spreads widened. The magnitude depends on concurrent ECB policy stance and global risk sentiment.