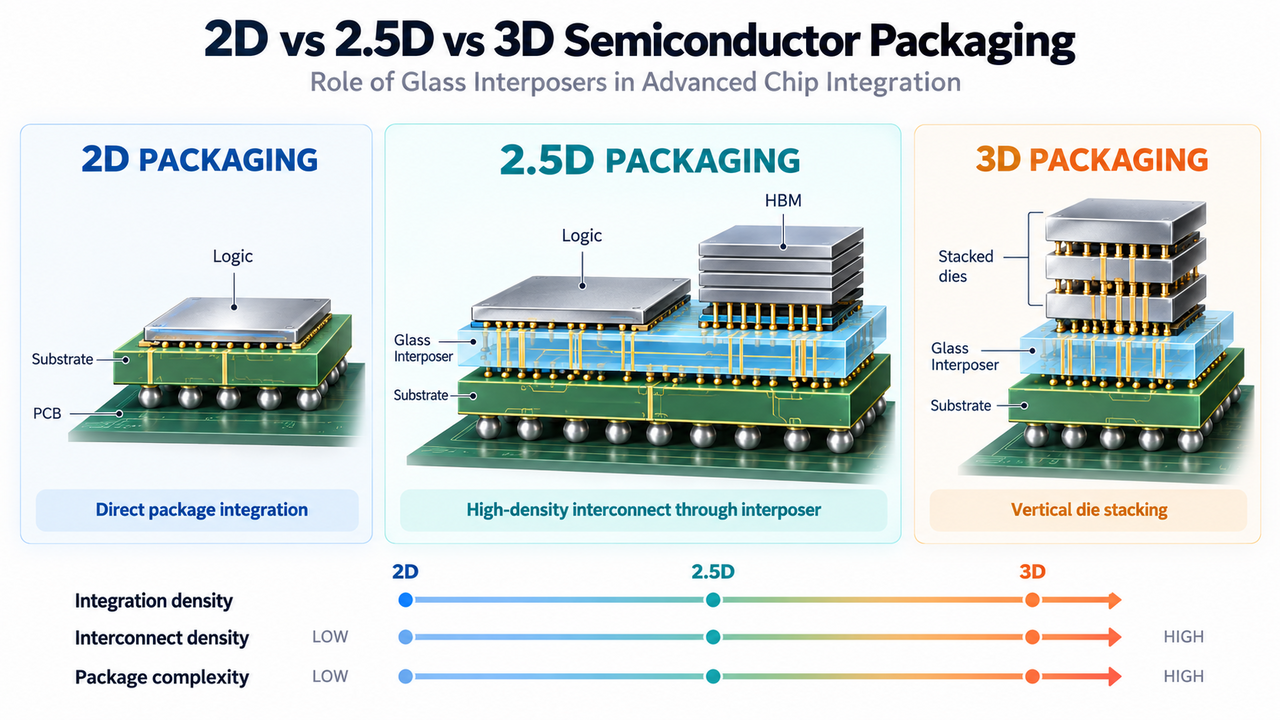
SK Hynix reported record quarterly profit on October 28, 2026, driven by explosive AI memory demand that lifted operating margins to historic highs, signaling sustained pricing power for high-bandwidth memory and triggering broad semiconductor sector repricing across global equity markets.
SK Hynix Market Impact: AI Memory Cycle Drives Sector Repricing
The South Korean memory giant's earnings beat reflects a structural shift in semiconductor demand dynamics. High-bandwidth memory (HBM) — critical for AI accelerators — now commands premium pricing that offsets traditional DRAM cyclicality. This margin expansion ripples through the supply chain, benefiting equipment makers like ASML and Tokyo Electron while pressuring foundry capacity allocation at TSMC and Samsung Foundry.
Capital intensity is rising in parallel. SK Hynix's capex guidance implies sustained investment in advanced packaging and HBM3E production, mirroring the financing strategies seen across the AI semiconductor ecosystem. The recent Broadcom $21B obligatielening financiert AI-chipovername strategie underscores how debt markets are funding AI infrastructure build-outs at scale.
"SK Hynix's margin trajectory confirms HBM has decoupled from commodity DRAM cycles. The market is pricing in a multi-year structural shortage where pricing power shifts decisively to memory suppliers with advanced packaging yield." — Senior Semiconductor Analyst, Global Equity Research
Regional equity flows reflect this divergence. Korean Kospi semiconductor heavyweights outperformed broader Asian indices, while U.S. chip stocks rallied on sympathy momentum. European semiconductor equipment names gained on expectations of sustained tool demand. The Broadcom capta US$ 21 bi em bonds para chips de IA further validates credit market appetite for AI-exposed issuers.
Key Takeaways for Semiconductor Investors
- Monitor HBM3E qualification timelines at major hyperscalers — revenue visibility extends 12-18 months beyond traditional DRAM booking windows.
- Watch advanced packaging capacity utilization rates at OSAT providers; bottleneck relief here determines HBM supply elasticity through 2027.
- Expect continued capex escalation across memory peers as Samsung and Micron accelerate HBM roadmaps to defend market share.
- Hedge cyclical DRAM exposure via equipment and materials suppliers whose revenue correlates with structural AI investment rather than consumer electronics cycles.
Frequently Asked Questions
Will SK Hynix Sustain Record Margins Through 2027?
Analyst consensus projects margin expansion through 2026 as HBM mix shifts toward higher-value HBM3E and HBM4 products. However, margin sustainability depends on yield improvements in advanced packaging and the pace of competitor capacity additions from Samsung and Micron.
How Does AI Memory Demand Affect Broader Semiconductor Valuations?
AI memory strength creates a positive read-across for logic foundries, equipment makers, and power semiconductor suppliers. Valuation multiples for AI-exposed semiconductor names have re-rated 15-20% above historical averages, reflecting structural growth premium over cyclical peers.