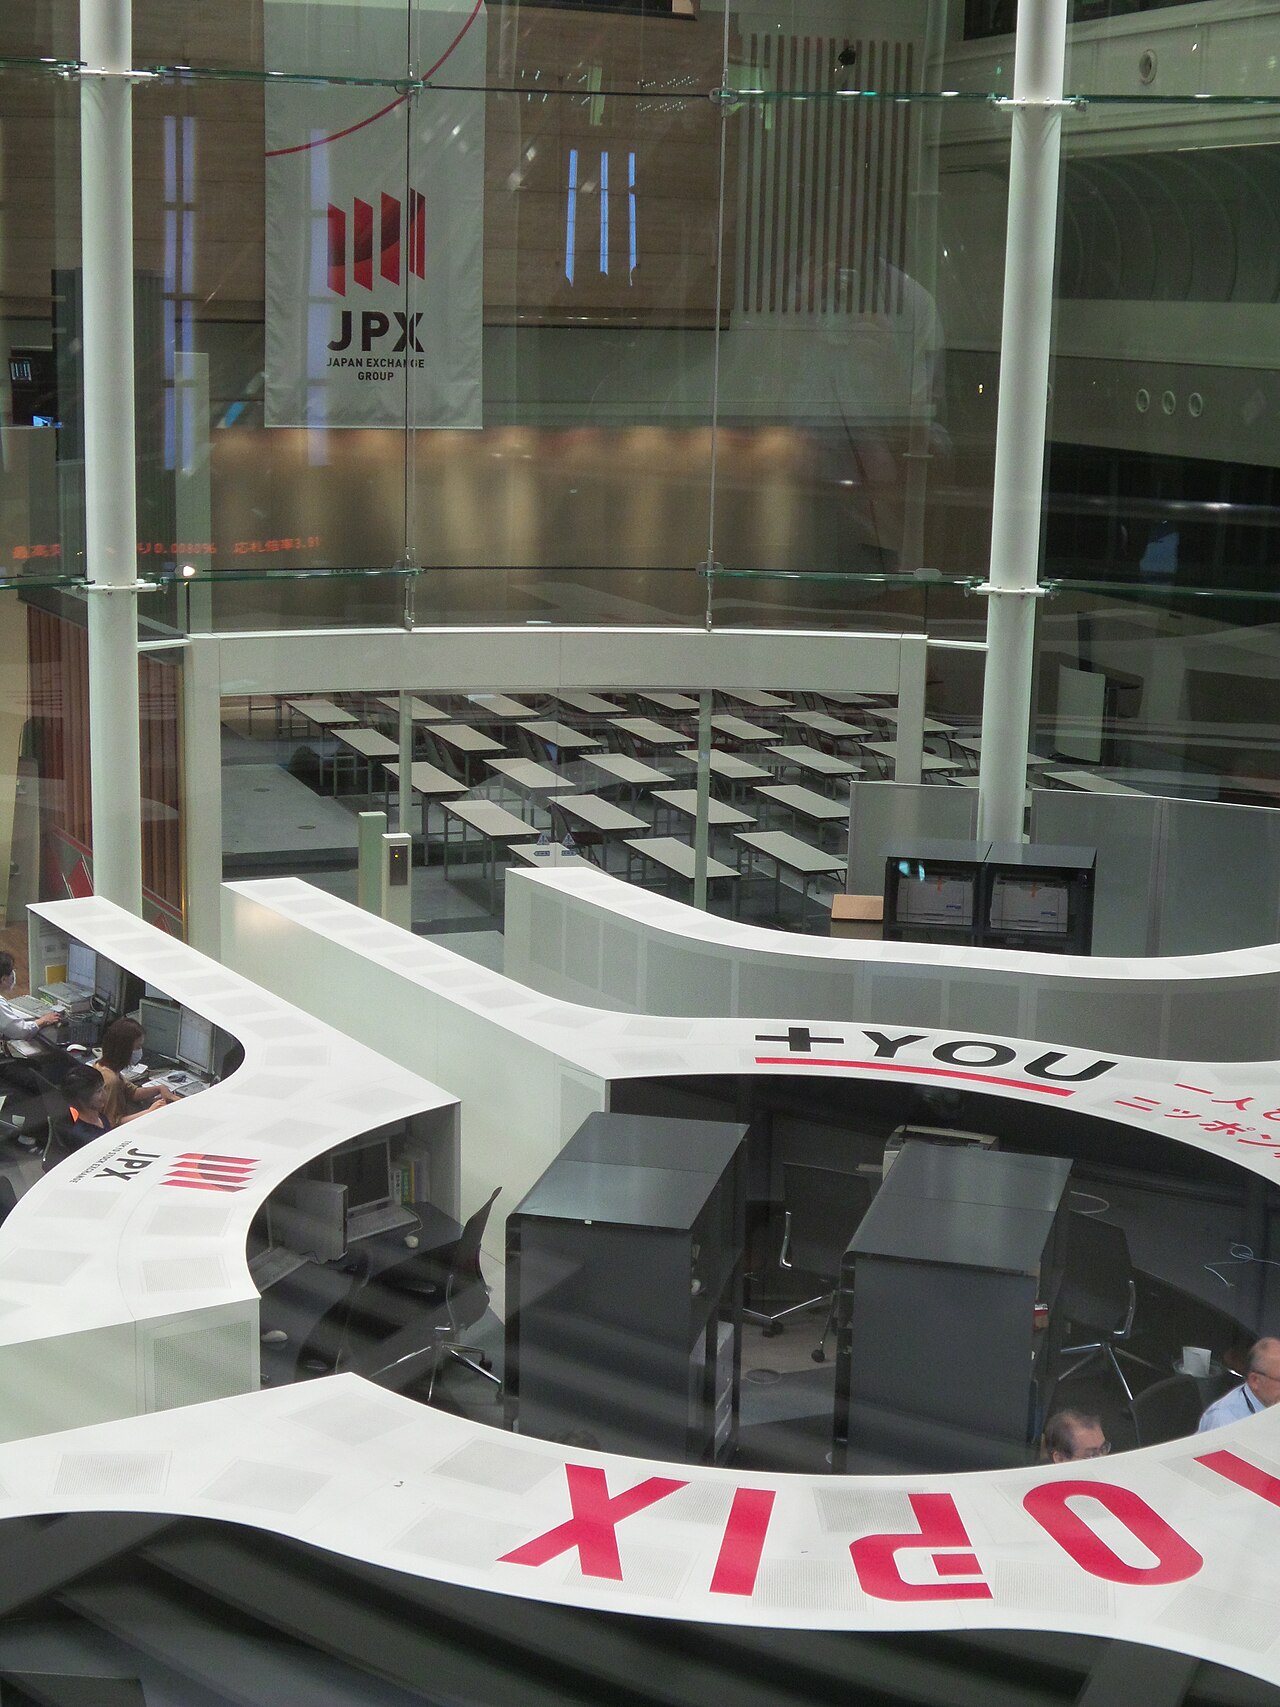
On October 30, the Bank of Japan unexpectedly accelerated its exchange-traded fund divestment program, yet the Topix index demonstrated resilience as investors bet on sufficient market liquidity to absorb the additional supply without destabilizing valuations.
The central bank's decision to hasten the unwinding of its ¥37 trillion ETF portfolio marks a pivotal transition from crisis-era stimulus to balance-sheet normalization. Historically, the BOJ emerged as the dominant marginal buyer of Japanese equities following the 2013 launch of quantitative and qualitative easing, accumulating holdings equivalent to roughly 8% of the domestic market capitalization. This latest move signals policymaker confidence that corporate governance reforms, robust buyback activity, and foreign inflows have deepened the buyer base enough to offset the withdrawal of the single largest participant. The market's muted reaction contrasts sharply with the 2021 taper tantrum fears, suggesting a structural shift in price discovery mechanics.
Market Impact & Transmission Channels
The transmission mechanism operates through three primary channels. First, reduced BOJ demand compresses the equity risk premium by forcing price-sensitive investors to assume marginal pricing authority, a dynamic that typically elevates volatility but improves allocative efficiency. Second, the sales coincide with the BOJ's gradual exit from yield-curve control, creating a dual tightening impulse where rising JGB yields compete for domestic institutional capital previously channeled into equities. Third, the pace of divestment influences foreign portfolio flows; overseas investors, who account for over 60% of Topix trading volume, interpret orderly absorption as validation of Japan's corporate governance renaissance, potentially unlocking further strategic allocations.
The market's ability to digest accelerated BOJ selling without a liquidity vacuum confirms that price discovery has migrated from policy-dependent to fundamentals-driven, a threshold crossed only when buyback yields exceed the cost of equity.
Sectoral dispersion reveals nuanced winners: financials benefit from the steepening yield curve, while high-dividend value names attract income-focused rotation. Conversely, growth-oriented sectors with elevated BOJ ownership concentrations face transient overhang risk until passive index rebalancing absorbs the float expansion.
Key Takeaways for Investors
- Monitor: The weekly BOJ ETF purchase/sale disclosure for deviation from the accelerated schedule, particularly any suspension triggered by Topix volatility exceeding 20%.
- Expect: A re-rating of Japanese equity risk premiums toward developed-market averages as the policy put expires, compressing the valuation discount to the S&P 500.
- Assess: Portfolio exposure to BOJ-heavy ETF constituents (e.g., 1321, 1579) for tracking error risk during quarterly index reconstitutions.
- Evaluate: Increasing allocation to shareholder-return-focused strategies, as corporate buybacks now exceed BOJ net selling by a 3-to-1 margin, becoming the primary marginal bid.
Frequently Asked Questions
Why did Japanese stocks rise despite the BOJ selling more ETFs?
Investors interpreted the accelerated sales as a vote of confidence in market depth, signaling the BOJ believes private demand — driven by corporate buybacks, pension fund reallocation, and foreign inflows — can absorb supply without policy support, removing a long-standing structural overhang.
How large are the BOJ's ETF holdings relative to the market?
As of October 2026, the BOJ holds approximately ¥37 trillion in ETFs, representing roughly 8% of total Japanese market capitalization and making it the largest single shareholder in over 40% of Nikkei 225 constituents, though net annual sales now run below 0.5% of average daily trading volume.