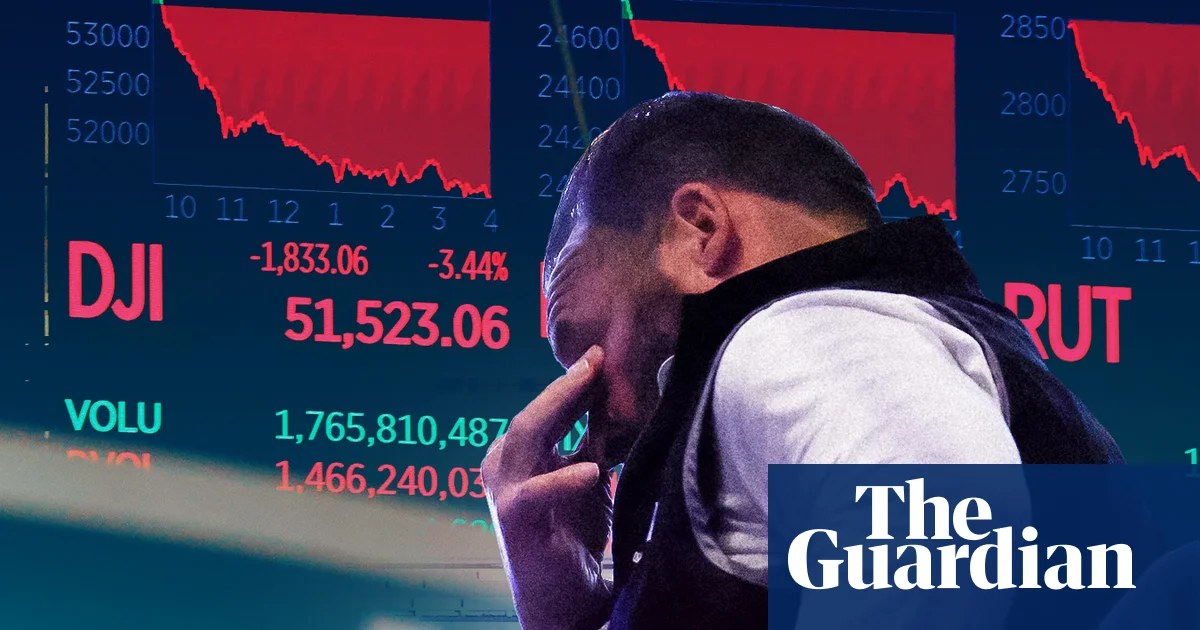
Global technology equities plunged in the wake of the Democratic Party's 2026 midterm election victory, erasing roughly $1 trillion in market value from Apple, Tesla, and Nvidia in a single session as investors priced in aggressive congressional oversight of artificial intelligence infrastructure and antitrust enforcement.
Key Takeaways
- Democratic midterm victory triggered ~$1tn single-session market cap loss across Apple, Tesla, Nvidia
- Market pricing in antitrust investigations, data center moratoriums, and capital gains tax reforms
- Regulatory drag raises WACC for long-duration AI growth assets, compressing terminal values
- Key milestones: House Judiciary subpoena calendar (Jan 2027), Senate data center markup, Q4 earnings guidance
- Credit markets calmer than equities, viewing regulatory risk as manageable for cash flows but destructive to equity optionality
Executive Intelligence Brief
Electoral Trigger and Immediate Market Reaction
The Democratic sweep of both congressional chambers has fundamentally altered the regulatory calculus for the technology sector. Market participants moved rapidly to discount the probability of legislative gridlock that had previously shielded mega-cap tech from meaningful federal oversight. The $1 trillion single-session contraction across the three largest AI-exposed names represents one of the most concentrated wealth destruction events in recent market history, exceeding the aggregate market capitalization of many G20 equity markets.
Senior economics correspondent Richard Partington noted the velocity of the repricing suggests algorithmic and systematic funds led the exit, liquidating long positions built on the assumption of a perpetually permissive regulatory environment. The selloff was not confined to semiconductor manufacturers; cloud infrastructure providers and vertical AI application layers saw correlated declines, indicating a sector-wide risk reassessment rather than idiosyncratic company news.
Regulatory Grounds for Enforcement
The incoming Democratic majority has signaled intent to pursue three distinct policy vectors. First, the House Judiciary Committee is expected to revive and expand antitrust investigations into vertical integration across chips, cloud, and foundation models. Second, the Senate Commerce Committee is drafting legislation that could impose moratoriums on new hyperscale data center construction pending environmental impact reviews, directly constraining the compute capacity growth baked into consensus revenue forecasts. Third, the Ways and Means Committee may advance mark-to-market taxation on unrealized capital gains for ultra-high-net-worth individuals, disproportionately affecting founder-led tech equity concentrations.
These measures collectively threaten the 'flywheel' dynamic where cheap capital funds compute build-out, which drives model performance, which attracts enterprise adoption, which justifies higher multiples. A Democratic Congress with subpoena power and legislative agenda control can interrupt this cycle at multiple points.
Transmission to Valuation Frameworks
Equity analysts are now revising terminal growth assumptions for AI infrastructure names. The introduction of regulatory drag — whether through enforced data locality requirements, mandatory algorithmic auditing, or compute allocation mandates — increases the weighted average cost of capital (WACC) for the sector. Higher discount rates applied to distant cash flows disproportionately punish long-duration growth assets, explaining the outsized impact on companies like Nvidia where the bulk of discounted cash flow value resides beyond year five.
Credit markets have so far remained orderly, with investment-grade tech spreads widening only modestly. However, high-yield issuers dependent on AI capex cycles for revenue visibility are seeing increased scrutiny from leveraged loan investors. The divergence between equity and credit signals suggests fixed income markets view the regulatory threat as manageable for cash flow generation but destructive to equity optionality.
Forward Outlook and Monitoring Milestones
The critical near-term catalysts are procedural. The House Judiciary Committee's organizational meeting in January 2027 will set the subpoena calendar. The Senate's first markup of the Data Center Environmental Accountability Act will reveal the stringency of permitting requirements. Meanwhile, Q4 2026 earnings calls — particularly from Nvidia, Microsoft, and Alphabet — will provide the first management guidance incorporating regulatory cost scenarios. Investors should watch for changes in capex guidance language, specifically any shift from 'demand-constrained' to 'permit-constrained' or 'power-constrained' frameworks.