Apple posted fiscal third-quarter revenue of $114.5bn, surpassing Wall Street expectations, but Chief Executive John Ternus warned that memory chip prices are rising at an 'unprecedented' rate as AI datacentres compete for supply, signalling margin pressure in the current quarter.
Key Takeaways
- Q3 revenue $114.5bn (+12% YoY) and EPS $2.10 beat consensus of $113.4bn/$1.99
- CEO John Ternus warns 'unprecedented' memory chip price rises will compress Q4 margins
- AI datacentre demand ('RAMageddon') driving component cost inflation across supply chain
- June/September price hikes on iPad, MacBook, iPhone providing partial offset only
- iPhone Duo foldable early interest but screen crack reports emerge; not yet in full release
Executive Intelligence Brief
Earnings Beat Offset by Component Cost Warning
Net income rose 12% to $30.71bn, or $2.10 per share, compared with $27.47bn, or $1.85 per share, a year earlier. Revenue climbed 12% from $102.5bn. Both figures exceeded FactSet consensus estimates of $1.99 EPS on $113.4bn revenue. The results bucked a weaker trend across big tech, where Alphabet, Amazon and Intel all disappointed this quarter.
Shares nevertheless slipped 2.75% in after-hours trading as Ternus, who assumed the chief executive role in September, flagged the memory cost trajectory. "What we're seeing with memory pricing right now is unprecedented," he told analysts on the earnings call, predicting fourth-quarter memory costs would exceed the prior three months.
AI Datacentre Demand Drives 'RAMageddon' in Supply Chain
The industry-wide squeeze, dubbed 'RAMageddon' by market participants, stems from voracious demand for high-bandwidth memory from AI datacentre operators. That demand is crowding out supply for consumer device makers, pushing up spot and contract prices for DRAM and NAND. Apple's exposure is significant given the memory intensity of iPhones, Macs and iPads.
Ternus said price increases implemented on iPad and MacBook lines in June, followed by iPhone increases in September, had "provided some offset" to the rising bill of materials. However, the lag between component cost inflation and retail price adjustments means near-term gross margins will absorb the spread.
Product Mix and Geographic Performance
Revenue growth was driven primarily by iPhone sales and strong Mac Mini demand, which Quilter Cheviot's Ben Barringer noted benefits from 'agentic AI' use cases. China growth was described as robust, a positive signal after previous quarters of concern. Conversely, iPad and wearables disappointed, while services revenue grew 10%, below the corporate average.
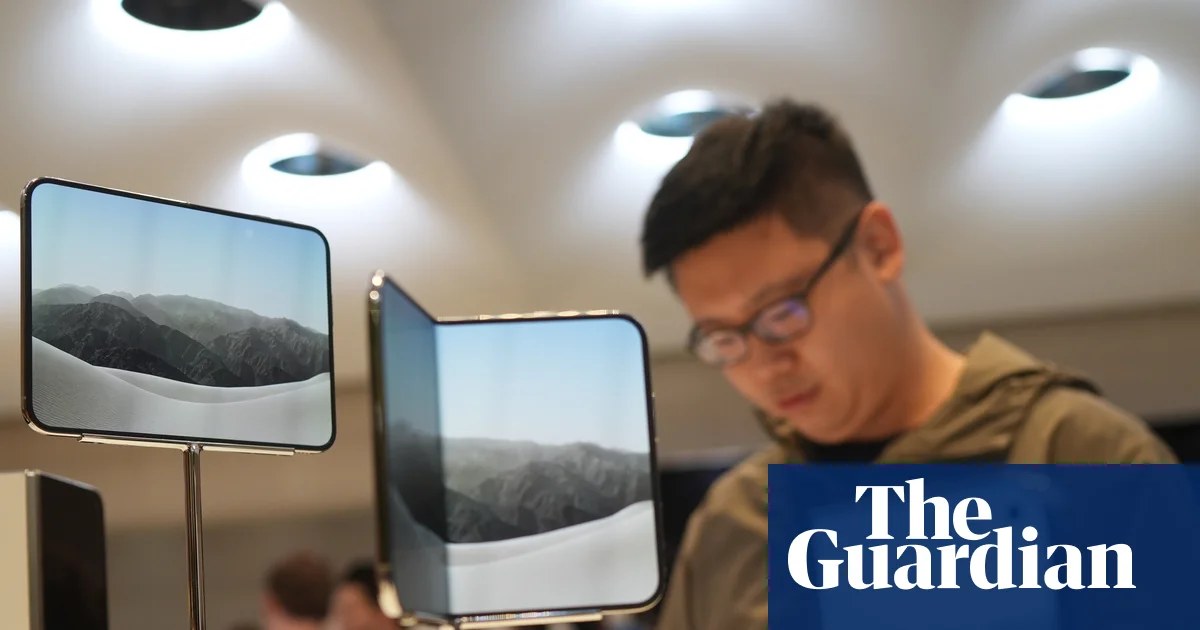
Barringer characterised the results as "OK, if on the disappointing side," citing the services deceleration and wearables weakness. He noted early interest in the iPhone Duo, Apple's first foldable handset, but cautioned "it is early days yet with the product not yet on full release."
Foldable Launch Quality Scrutiny and Leadership Transition
Separate reports indicate some iPhone Duo owners are reporting screen cracks, adding execution risk to the new form factor's ramp. The product's success is seen as critical to the "next leg of Apple's product innovation," per Barringer.
The quarter also marked the formal transition of Tim Cook to Executive Chair, accompanied by a $47m compensation package. Cook's tenure as CEO ended with Apple becoming the second company to reach a $5tn market valuation, though shares have recently retreated as investors rotate away from AI-heavy names.
Outlook: Margin Trajectory and AI Strategy Differentiation
Emarketer analyst Jacob Bourne highlighted that Apple's "tepid approach" to AI infrastructure spending has preserved cash flow relative to peers investing tens of billions in datacentre buildouts. Partnerships with firms such as Alphabet may allow Apple to integrate AI capabilities without commensurate capital intensity.
Key variables for the coming quarter: the precise gross margin impact of memory costs, iPhone Duo defect rates and return volumes, and whether China's robust growth trajectory sustains amid macroeconomic headwinds. The company also faces a £1.5bn regulatory ruling in the UK it is seeking to appeal.